Thinking about buying a Tenancy-in-Common (TIC) in San Francisco, but unsure how it compares to a condo? You are not alone. A TIC is a genuine path into buildings and blocks that would otherwise be out of reach, and it comes with a different ownership structure, a different loan, and a different resale picture than a condo.
This guide covers what a TIC actually is, how the agreement governs your rights, what to check before you write, and how TICs compare to condos across the city. For the loan side in detail, including what fractional lenders require of the building and of you, see my separate guide to TIC financing in San Francisco.
The Basics
What Is a TIC?
A Tenancy-in-Common (TIC) is shared ownership where you and other owners each hold a fractional interest in the entire property, not an individually deeded unit as in a condo. Your rights to occupy a specific unit and share costs are set by the recorded TIC agreement.
You are not buying a unit. You are buying a share of a building, plus the recorded right to live in one part of it.
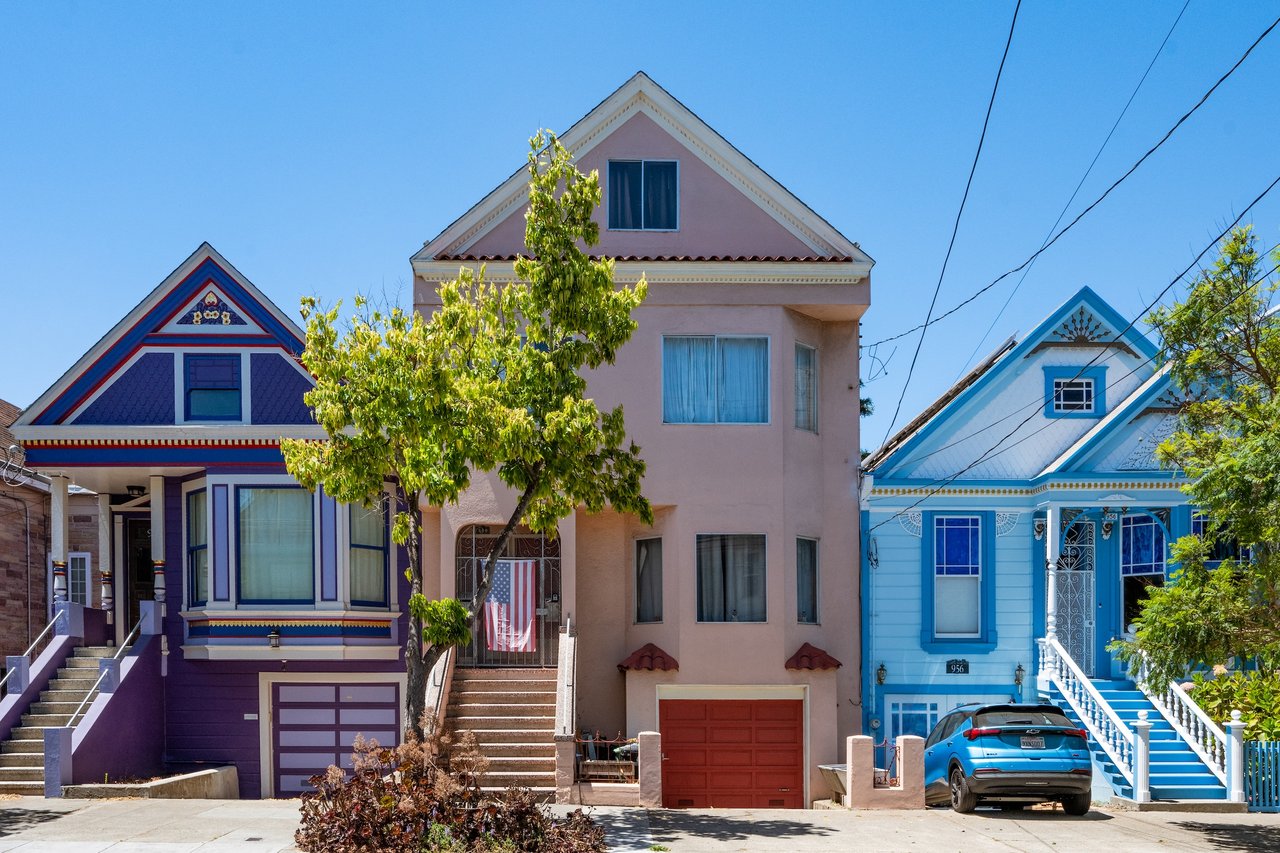
TICs are common in San Francisco multi-unit buildings, concentrated in the Mission District, Hayes Valley, Lower Pacific Heights, Cole Valley, and the Inner Sunset.
Each owner occupies a designated unit but owns and maintains the property together, with rules on everything from leasing to maintenance set by the TIC agreement.
TICs became popular because they allowed residents to co-own homes without condo conversion. The practice remains active across much of the city, from the Mission and Hayes Valley to the Richmond and Sunset.
Ownership
How TICs Work in San Francisco
Your fractional interest and the TIC agreement are recorded with the property. Lenders, title companies, and attorneys use them to define your legal rights.
- ✓Request the full TIC agreement and any amendments.
- ✓Ask whether the building has already been reviewed and approved by a fractional lender.
- ✓Review permits, litigation, conversions, and all disclosures before making an offer.
Financing
Financing a TIC in San Francisco
TIC financing is standard here and has been for well over a decade. Nearly every TIC sold in San Francisco today is bought with a fractional loan: you borrow individually against your own percentage interest, qualify on your own income and credit, and sign your own note with no legal connection to your neighbors' loans.
The short version
Your note is your own
Under a fractional loan, a neighbor's default is their lender's problem, not a claim on your loan or your share. Shared group mortgages, where one loan covered the whole building, are a legacy structure and are rare in current inventory, but they do still exist, so confirm which structure a building uses before you write.
Underwriting is stricter than a conforming loan on a condo, and the lender reviews the building as well as the borrower. For building eligibility, credit and reserve requirements, and how pricing compares to a condo loan, read how TIC financing works in San Francisco.
Documents Lenders Will Review
- ✓Recorded TIC agreement and amendments
- ✓Completed TIC questionnaire for the building
- ✓Master insurance coverage
- ✓Reserve documentation and budgets
- ✓Rental history, if applicable
- ✓Title reports and pending assessments
Side by Side
TICs vs. Condos: Key Trade-Offs
| TIC | Condo |
|---|---|---|
Price | A share trades at a discount to an otherwise identical condo in the same building type and neighborhood. That discount is the trade you are being offered. | Full market price for the same building type and neighborhood, with no TIC discount. |
Financing | A smaller set of specialist lenders, rates above conforming, more equity down. See the detail here. | Wider access to conventional loans. |
Liquidity and Resale | A smaller buyer pool, so marketing matters more and sales can take longer. | Resells into a broader pool. |
If a Co-Owner Defaults | Under a fractional loan, each owner's note is separate. Under a legacy shared group mortgage the risk is genuinely shared, which is why confirming the loan structure is a due-diligence item, not a formality. | Each owner's loan is separate. A neighbor's default does not reach your financing. |
Governance | Cooperation, and for major decisions the voting thresholds written into the agreement. | Run by an HOA using CC&Rs and by-laws. |
Maintenance and Reserves | Reserve funds and upkeep standards vary by building. | Typically formal budgets and reserve studies. |
Tenant and Rent Control | San Francisco tenant protections and rent control laws can affect TIC buildings. Check resident status, leases, and rules citywide. | The same city protections attach to the building and its units. |
Title and Conversion | Title insurance may be different. Conversion is possible but requires city approval and a lengthy process, and should never be the basis of your purchase decision. | Separately deeded from the start, with no conversion question to answer. |
For a worked example of how a TIC is priced against comparable condos, see my Cole Valley case study on 449 Frederick Street, or browse what San Francisco and Marin homes have sold for.
Before You Write
Citywide TIC Due Diligence Checklist
- ✓Current deed for your fractional interest, and an updated title report
- ✓Full TIC agreement and amendments
- ✓Confirm the loan structure: fractional, or a legacy shared group mortgage
- ✓Ask whether the building is already approved with a fractional lender
- ✓Review for easements, liens, litigation
- ✓Get financing pre-approval from an SF TIC lender before you tour seriously
- ✓Occupancy rules, and buy/sell and transfer restrictions
- ✓Reserve funding and voting rules
- ✓Comprehensive building inspection, especially seismic, plumbing, electrical
- ✓Request maintenance records and reserve study
- ✓Confirm insurance details, including earthquake and replacement-cost coverage
- ✓Review tax assessments and any recent changes
- ✓Rent control and lease status for any occupied units
- ✓Condo conversion status, and the city process if relevant
- ✓Disclosure of disputes, meeting notes, sales history, any arrears
- ✓Meet key co-owners when possible to gauge group dynamics
Practical Tips
Three Habits That Protect You
01
Keep Your Contingencies
Include inspection and financing contingencies.
02
Ask Early
Request full TIC disclosures and documents up front.
03
Use a TIC Attorney
Use an attorney who specializes in SF TICs before removing contingencies or closing.
Next Steps
Moving Forward With Confidence
No matter where you are buying in San Francisco, from Mission flats to Richmond duplexes or Sunset triplexes, early planning makes all the difference.
- ✓Speak with a TIC-savvy lender before writing offers, and read how TIC financing works first so you know what to ask.
- ✓Engage a real estate attorney for document review.
- ✓Use a title company experienced in TIC insurance across San Francisco.
As your advisor, I help you source, vet, and negotiate San Francisco TICs citywide. My job is to make sure your experience is smooth, transparent, and well-supported every step, from first search to closing day.
Already Own a TIC Share?
Financing availability is the single biggest driver of what your share is worth. Get a valuation and I will tell you how your building is positioned.
Questions Buyers Ask
FAQs
What is a TIC and how does it differ from a condo?
Are TICs harder to resell than condos?
Can a TIC convert to condos in San Francisco?
Does rent control apply to a TIC building?
Do I need a TIC attorney?
What issues should I check for in any SF TIC?
Ready to Review a Building?
Tell me which property you are looking at, or ask about off-market options. I will tell you what I know about the building and what it means for your timeline.
Broker Associate, Vanguard Properties
CA DRE #01388135
(415) 244-5846 | [email protected]
burgelmanhomes.com
Oliver Burgelman is a Broker Associate with Vanguard Properties, CA DRE #01388135, working San Francisco and Marin exclusively since 2003. This article is general information about tenancy-in-common ownership in San Francisco and is not legal, tax, or lending advice. TIC agreements, city requirements, and loan guidelines vary and change without notice. Have a qualified San Francisco TIC attorney and lender review the specific building and documents before you remove contingencies.